


Featured Summary:
- Moniepoint UK is tightening remittance security as open banking moves deeper into cross-border payments.
- African fintech growth is entering a tougher phase where trust and security decide scale.
- Fintech security is becoming infrastructure against fraud, payment errors, and identity abuse.
- Moniepoint’s UK push signals a broader African fintech move into regulated European markets.
Cross-border payments are becoming harder to win on price alone.
As regulators tighten oversight and fraud controls across international payment corridors, remittance providers are being pushed to compete on verification and transaction integrity.
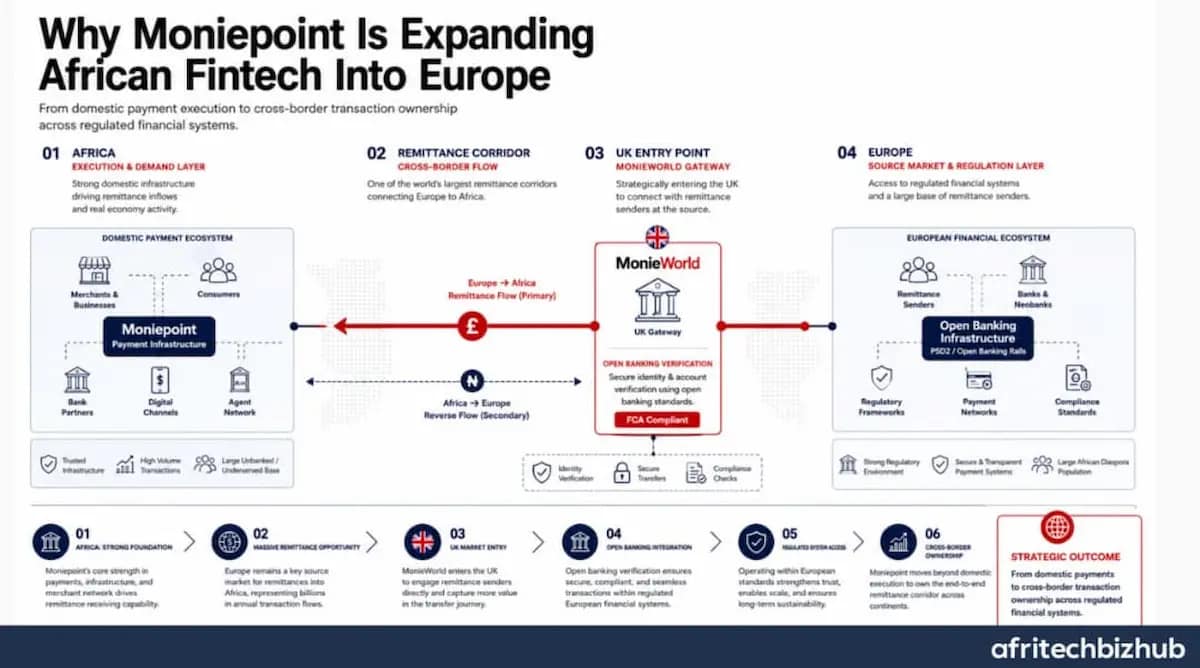
Through MonieWorld, Moniepoint is strengthening UK remittances with open banking account verification that checks recipient details before transfers are completed.
The move positions security as infrastructure, not a feature, and signals a broader shift as African fintech firms expanding into Europe face higher operating standards than growth alone can satisfy.
How Is Moniepoint Improving Africa Payments Security?
Moniepoint is improving payment security in its UK remittance business by introducing recipient account verification before transfers are completed.
Through MonieWorld’s partnership with tell.money, the company is integrating the UK’s Confirmation of Payee system, allowing users to check that recipient account details match before money is sent.
The measure targets one of the most persistent risks in cross-border payments: sending money to the wrong account.
The rollout expands Moniepoint’s security controls inside the transaction process rather than after settlement.
For Moniepoint UK, the move places remittance verification alongside transfer execution as the company deepens its presence in regulated payment markets.
Why Is African Fintech Moving Into Cross-Border Payments?
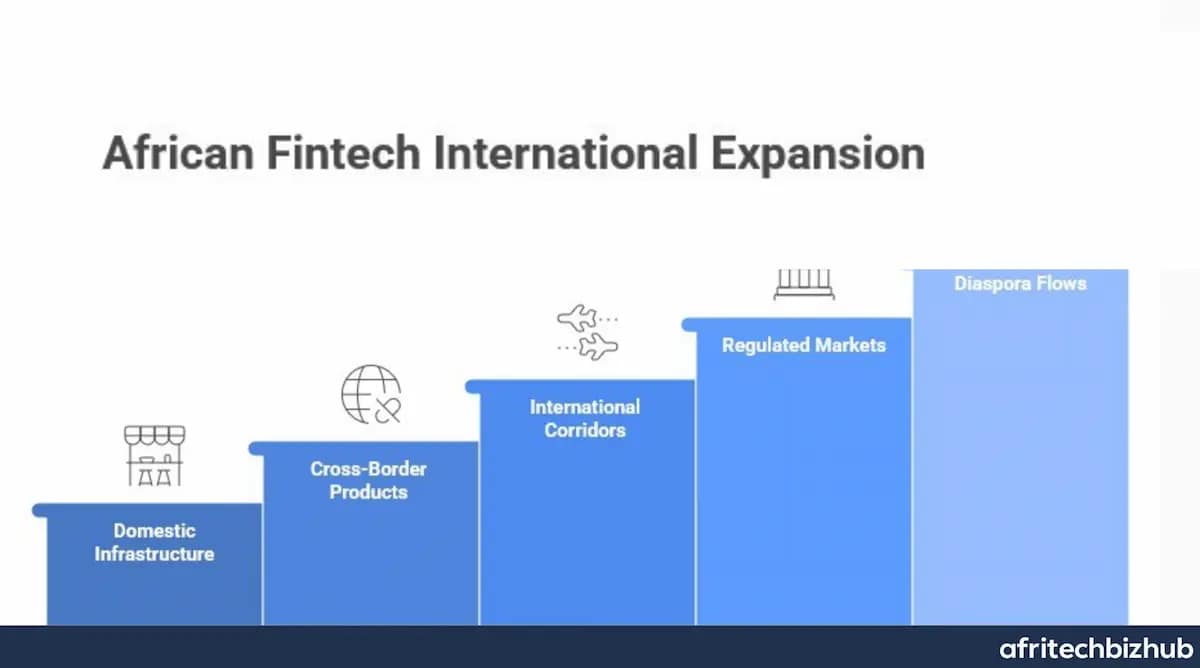
African fintech growth is moving into international payment corridors where transaction volumes and customer relationships extend beyond national markets.
Expansion is increasingly coming from firms turning domestic payment infrastructure into cross-border financial products rather than competing for the same local users.
Moniepoint’s UK expansion follows that direction.
Through MonieWorld, the company entered UK remittances and paired market entry with open banking verification instead of competing on transfer speed alone.
The move shows how African fintech firms are widening distribution through regulated markets and diaspora money flows.
How Does Fintech Security Reduce Cross-Border Fraud in Africa?
Cross-border fraud persists where payment instructions move faster than verification.
The UK Payment Systems Regulator introduced Confirmation of Payee to reduce authorised push payment fraud by requiring account-name checks before transfers are executed.
The principle is straightforward: validate the destination before releasing funds.
That approach is becoming more relevant across African fintech as remittance and international payment volumes expand.
Moniepoint’s UK remittance rollout shows how payment providers are moving fraud controls closer to transaction initiation rather than depending on dispute resolution after settlement.
Verification reduces failed transactions, refund costs, fraud exposure, and customer abandonment before errors become cross-border disputes.
Why Is Moniepoint Expanding African Fintech Into Europe?
Moniepoint is expanding into Europe to move closer to where remittance decisions are made.
Through MonieWorld, the company entered the UK market to serve users sending money to Nigeria and introduced open banking verification as part of the transfer process.
The expansion gives Moniepoint direct exposure to one of the world’s largest remittance corridors while operating inside established payment standards.
The move extends African fintech beyond domestic payment execution into customer acquisition and transaction ownership across borders.
For Moniepoint UK, Europe is not an export market; it is a source market for remittances and a larger test of whether African fintech can compete inside regulated financial systems.


Recent Comments