

Featured Summary:
- The Middle East war is adding pressure to emerging-market investment as energy prices and global financing costs rise
- Currency depreciation threatens foreign investors’ returns, making exchange-rate stability critical to attracting capital
- Electricity shortages and high production costs risk holding back industrial investment across developing economies
- Heavy government borrowing threatens to keep business lending expensive and restrict private-sector expansion
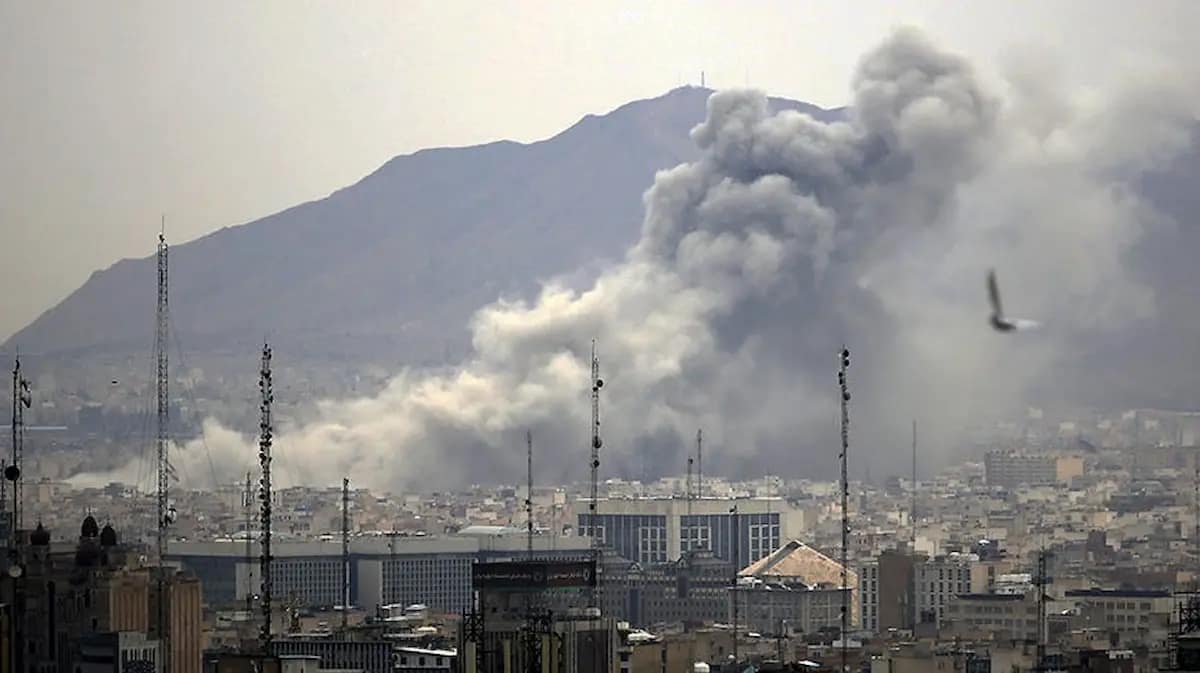
The Middle East war has driven up oil prices, raising inflation concerns and putting pressure on borrowing costs worldwide.
Foreign investors withdrew $26.3 billion from emerging-market stocks and bonds in September, according to the Institute of International Finance.
The withdrawals come as several developing economies struggle to attract investment beyond government securities.
Currency losses threaten returns on financial assets, while electricity shortages and expensive credit make it harder for businesses to expand.
The International Monetary Fund’s April 2026 Global Financial Stability Report found that countries with stronger financial institutions, larger reserves and lower fiscal risks were better able to withstand withdrawals by foreign investment funds.
For investors buying local-currency assets in Egypt, Nigeria and Argentina, exchange-rate movements remain a major consideration.
High domestic yields offer little protection when depreciation reduces the value of earnings converted into dollars.
Currency Losses Threaten Returns on Emerging-Market Investments
Foreign holdings of Egyptian debt instruments approached $40 billion in September 2026.
The Central Bank of Egypt maintained deposit and lending rates at 19% and 20%, respectively, while net international reserves reached $57.35 billion, compared with $49.54 billion a year earlier.
The larger reserves have given Egypt more capacity to meet foreign-currency obligations. Investors purchasing Egyptian Treasury securities, however, still face the risk that depreciation will reduce their dollar earnings when they sell their holdings.
Nigeria’s naira traded around ₦1,330 per dollar in late September, with external reserves exceeding $54 billion.
The central bank reduced its benchmark interest rate to 23% during the month, while the 364-day Treasury bill cleared at 15.90% at the October 14 auction.
Bids for the one-year instrument reached ₦982.21 billion against ₦350 billion offered, with ₦220 billion allotted.
The figures establish demand for naira-denominated debt but do not identify foreign participation.
Investors entering the market at that yield would still need the currency to remain sufficiently stable to preserve their dollar returns.
Argentina has continued buying foreign currency to rebuild reserves while operating an exchange-rate band.
Purchases exceeded $14.5 billion during 2026, although annual inflation remained at 33.5% in August and the peso traded near 1,536 per dollar on September 23.
BBVA Research projected the exchange rate reaching 1,630 pesos per dollar by December, with inflation slowing to 29%.
Investors holding peso-denominated assets therefore face the possibility of further currency losses despite the government’s efforts to strengthen reserves.
Egypt’s foreign debt holdings indicate that international investors are still prepared to buy local securities despite exchange-rate exposure.
Nigeria’s auction data show demand without establishing how much came from abroad. Argentina’s projected depreciation leaves greater uncertainty over the dollar value of peso investments.
For companies considering factories and other long-term projects, currency movements are only part of the investment decision.
The cost of electricity, transport and industrial production also determines whether businesses can operate profitably.
Power Shortages and Weak Industrial Capacity Reduce Investment Returns
Power outages affected 82.5% of Nigerian businesses surveyed by the World Bank in 2025. Manufacturers relying on backup generators face additional fuel and maintenance expenses, increasing the cost of operating production facilities.
About 27.5% of surveyed Nigerian firms also identified transport infrastructure as a severe obstacle.
Poor road conditions and unreliable freight services can increase delivery expenses for manufacturers moving raw materials and finished products.
In Ethiopia, 85.9% of businesses surveyed in 2025 reported electricity interruptions. The country has developed industrial parks to attract manufacturing investment, but factories requiring continuous power remain exposed to supply disruptions.
Foreign-exchange shortages and transport costs have also complicated access to imported machinery and industrial inputs.
Morocco’s automotive industry has attracted international manufacturers and component suppliers serving European markets.
The Tanger Med port complex provides access to international shipping networks, while industrial zones support vehicle assembly and parts production. In the World Bank’s 2023 survey, 11% of Moroccan firms reported electricity outages.
Automotive exports reached 93.7 billion dirhams in the first half of 2026, up 17.4% from a year earlier, according to Morocco’s foreign-exchange office.
The additional costs facing manufacturers in Nigeria and Ethiopia can reduce the earnings available from new factories.
Morocco’s automotive exports show the scale of production supported by its industrial network, although export revenue does not establish individual companies’ profitability.
Access to affordable credit will also influence where businesses expand. In economies with substantial government borrowing requirements, banks’ purchases of sovereign securities can leave private companies competing for financing at higher interest rates.
Government Borrowing Competes With Private Businesses for Capital
Credit to Nigeria’s private sector fell from approximately ₦84.5 trillion in August to ₦83.9 trillion in September 2026, while net credit to the government increased from ₦117.5 trillion to ₦124.3 trillion, according to the Central Bank of Nigeria.
Average prime lending rates stood at 17.86% in August, with maximum rates reaching 29.20%. Banks also operated under a 45% cash reserve requirement.
The September credit figures show an increase in government financing alongside a decline in private lending, although they do not establish that banks redirected funds from businesses into sovereign securities.
In Ghana, private-sector credit grew 35.5% in the year to August 2026, reaching approximately GH¢123.3 billion, according to the Bank of Ghana.
Average commercial lending rates declined to 15.94% from 24.15% a year earlier, following the country’s sovereign debt restructuring.
Ghana’s 91-day Treasury bill yielded 5.38% in August. Lower government borrowing rates coincided with stronger private-sector credit growth, although the figures do not establish how much new lending financed industrial expansion.
Kenya’s average commercial bank lending rate fell to 14.34% in August, according to the Central Bank of Kenya.
The 91-day Treasury bill yielded 8.75% on October 19, leaving commercial borrowers paying higher rates than the government despite earlier monetary easing.
The International Monetary Fund reported in April that the Middle East war had slowed foreign-currency sovereign bond issuance and raised domestic yields in several emerging economies.
Banks in financially weaker markets also held greater exposure to government debt, increasing their sensitivity to sovereign financing requirements.
The extent to which public borrowing restricts business investment will depend on banks’ government securities holdings, private-sector credit growth and the financing requirements of individual economies.
Nigeria’s recent credit movements warrant closer examination, particularly if government borrowing continues rising while commercial lending weakens.
Emerging Markets Must Build Industries That Can Retain Foreign Capital
The United States attracts foreign investment partly because its financial markets offer access to profitable companies and established industries.
Investors can buy stakes in businesses, finance expansion and sell their holdings through markets with substantial trading activity.
That access gives American companies a financing advantage that many emerging economies have yet to develop.
For emerging markets, the opportunity lies in building businesses capable of attracting investment without relying on unusually high government bond yields.
Competitive manufacturing and reliable infrastructure can support commercial expansion, but investors also need confidence that contracts will be enforced and earnings can be repatriated.
Domestic financing will be important to that process. Banks that can extend affordable business loans and capital markets that support corporate fundraising would give companies more opportunities to expand without depending on government spending or foreign debt.
As those businesses grow, they can generate employment and raise productivity, strengthening the domestic economy’s capacity to finance further development.
Foreign investment would then support commercial activity rather than primarily helping governments meet borrowing requirements.
An end to the Middle East war could ease pressure on global financing, but it would not close the investment gap between developed and emerging economies.
Countries unable to establish profitable industries and dependable financial markets could continue paying more to attract foreign capital long after energy prices stabilize.


Recent Comments